
Most families rule it out before they’ve finished looking. The search for affordable home care near me starts with a number—an hourly rate on a website, a figure from a friend, an estimate someone mentioned at a doctor’s office—and ends with a quiet conclusion that professional care just isn’t realistic for their situation. The family adjusts. Someone drives over more often. A sibling changes their schedule. Everyone absorbs a little more than they were already carrying, and the idea of a professional caregiver gets filed away under “someday.”
What most of those families don’t know is that the number they found was only part of the picture. Financial programs—some federal, some through private insurance, some through care flexibility itself—can meaningfully change what home care costs for families who know to ask about them. Most families don’t know to ask. This blog post is written to change that.
The Assumption That Stops Families Before They Start
The most common financial misconception in home care is that you have to pay out of pocket, at full agency rates, for as many hours as a parent needs. That framing is understandable — it’s what most agency websites imply by default, and it produces a monthly number that genuinely is out of reach for many families.
But professional home care is rarely a single price point. It is a spectrum of options, coverage sources, and scheduling structures that, assembled thoughtfully, looks very different from the worst-case estimate most families form in the first hour of researching affordable home care near me.
Option 1: VA Benefits — The Most Underused Financial Resource in Home Care
If your parent is a Veteran or the surviving spouse of a Veteran, explore this first—and it’s the option that most consistently surprises families.
- The VA’s Aid and Attendance benefit is a pension supplement specifically designed for Veterans who need help with daily activities such as bathing, dressing, and getting around the home. It is not the same as the VA pension itself — it is a separate benefit added on top, and the monthly amounts can be substantial. Benefit levels vary based on the veteran’s marital status, number of dependents, income, and level of care need. Contact Assisting Hands™ or the VA directly for current eligibility figures and benefit amounts.
- The benefit requires an application, which is where most families stop. The process can feel bureaucratic, and without guidance, it often is. But the VA’s Veterans Programs also include two additional options worth knowing about:
- The VA Respite Care Program provides temporary relief to family caregivers of veterans — scheduled professional care coverage that gives the primary caregiver a meaningful break while ensuring the veteran continues receiving quality support. For veteran families concerned about caregiver burnout, this program can extend how long a family can sustain a home care arrangement without burning out.
- The Homemaker and Home Health Aide Care program provides eligible veterans with in-home assistance for daily tasks—housekeeping, meal preparation, personal grooming, and other essential activities—for those who may have difficulty doing them independently because of age, disability, or medical conditions.
Both programs have their own eligibility requirements based on service history, documented care needs, and financial factors. Assisting Hands® can help veteran families determine which programs apply to their situation.
Option 2: Long-Term Care Insurance — Already Paid For, Often Forgotten
Long-term care insurance is one of the most underutilized financial assets in home care. Millions of Americans over 65 hold LTC policies — purchased years earlier when a financial advisor or employer recommended it — and have never filed a claim.
Most LTC policies cover non-medical home care, though terms vary significantly by policy. The typical benefit trigger is the inability to perform two or more activities of daily living independently: bathing, dressing, eating, continence, mobility, or transferring. If your parent needs help with these tasks, they may already qualify to activate a benefit that pays a daily or monthly amount toward home care costs.
Before assuming home care is unaffordable, check whether your parent holds an LTC policy. Contact the insurance company directly to request a benefits summary and ask specifically whether in-home non-medical care qualifies under their specific policy terms — coverage details vary, so confirming directly with the insurer is essential.
Option 3: Medicaid and State Waiver Programs
Medicaid is the most frequently misunderstood benefit in home care. Most families associate it with nursing home coverage — not home care. In fact, Medicaid’s Home and Community-Based Services (HCBS) waiver programs fund non-medical in-home care for eligible individuals, keeping people out of facilities and in their own homes.
Eligibility for HCBS waiver programs is based on income, assets, and level of care need. The application process varies, and some areas have waitlists. For families at or near Medicaid income thresholds, these programs can cover a substantial portion of home care costs. Families should confirm whether their chosen home care provider accepts Medicaid funding, as provider acceptance varies.
Medicaid and Medicare are not the same. Medicare does not cover ongoing non-medical home care. Medicaid, through waiver programs, can. Knowing this distinction is one of the more important pieces of practical knowledge a family can have when evaluating whether affordable home care near me is genuinely within reach.
Option 4: Flexible Scheduling as a Financial Strategy
This option doesn’t come from a government program or an insurance policy. It comes from understanding what a care plan includes—and what it doesn’t.
Many families assume home care is an all-or-nothing proposition: either you hire full-time coverage, or you’re handling everything yourself. In practice, professional home care can start with as little as a few hours per week—companion care visits, medication reminders, meal preparation on days when family coverage isn’t available—and expand incrementally as needs change.
Starting with ten hours per week rather than forty reduces monthly cost by roughly 75 percent. For families who can cover some days themselves and use professional care to fill the critical gaps, this structure makes quality care genuinely manageable on a limited budget.
A care coordinator who understands your family’s actual availability — not just your parent’s needs — can build a schedule that works within a real budget rather than a theoretical one.
What Most Families Don’t Do — but Should
The families who find the most financially sustainable home care arrangements rarely do so by calling the first agency they find and asking for a rate. They are the ones who asked a more specific set of questions.
Before concluding that affordable home care near me is not realistic, it is worth finding out:
- Whether your parent is a Veteran or surviving spouse — and whether the Aid and Attendance benefit applies
- Whether any LTC insurance policy is held and what it covers
- Whether Medicaid HCBS waiver eligibility exists based on income and care need
- Whether a part-time or flexible schedule would meet the most important care needs within a realistic budget
These are not complicated questions. But they are the questions most families never ask — because most home care conversations start with a rate sheet, not a financial exploration.
A Free Conversation Is the Right Starting Point
For families beginning this process, the most useful first step is a conversation with a care coordinator who understands both the care side and the financial options side — someone who can look at your parent’s actual situation and help map what’s available.
Assisting Hands® Home Care offers free in-home assessments that cover both care needs and financial options, including VA benefit navigation for eligible veteran families. Care plans also flex—starting with a limited schedule and expanding as needs change —so families are never locked into more than they need.
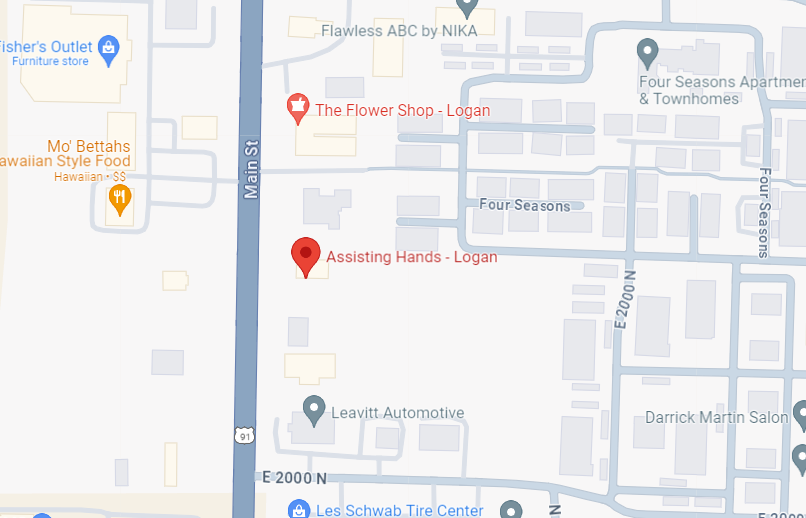
Call (435) 216-3216, visit 434 North 20 West, Smithfield, UT 84335, or reach out online. No obligation. Just an honest conversation.
Frequently Asked Questions
Q: Does Medicare cover home care costs?
A: Medicare does not cover ongoing non-medical home care — the daily personal assistance, companion care, and household support that most seniors need most. Medicare covers skilled home health care (nursing visits, physical therapy) when a physician orders it for a specific clinical need. For non-medical home care, Medicaid waiver programs, VA benefits, and long-term care insurance are the relevant financial options.
Q: What is the VA Aid and Attendance benefit and who qualifies?
A: Aid and Attendance is a VA pension supplement available to Veterans and surviving spouses who need help with daily activities such as bathing, dressing, eating, or getting around the home. Eligibility is based on service history, income, and level of care need. Benefit amounts for 2025 range from approximately $1,432 per month for a surviving spouse to $2,431 per month for a Veteran with a dependent. A VA-approved home care provider can help families begin the eligibility determination process.
Q: Can long-term care insurance be used to pay for home care?
A: Yes, in most cases. Most long-term care insurance policies cover non-medical in-home care when the policyholder cannot independently perform two or more activities of daily living. Contact the insurance company directly to request a benefits summary and confirm whether in-home care qualifies under the specific policy terms.
Q: Is part-time home care significantly cheaper than full-time?
A: Yes. Home care is typically billed hourly, so care costs scale directly with the number of hours scheduled. A family that uses ten hours per week of professional care — filling the gaps in their own coverage — pays roughly 75 percent less than a family using full-time coverage. Starting with a targeted, flexible schedule is one of the most effective cost management strategies available.
Q: What is a Medicaid HCBS waiver and how does it apply to home care?
A: Medicaid’s Home and Community-Based Services waiver programs fund non-medical in-home care for eligible individuals — typically based on income, assets, and level of care need. These programs vary by state and sometimes involve waitlists, but they can cover a substantial portion of home care costs for qualifying families. They are separate from Medicare and designed to support aging in place rather than facility placement.